Homebuilding’s belles-of-the-ball mergers-and-acquisitions pandemic surge has recently entered an inflection zone marked by a reset of acquirer and seller dynamics, imbalances in available capital, and shifting drivers of motivation and urgency.
Global investors are reshaping U.S. homebuilding, land development and build-to-rent. The implications extend beyond who buys whom to include who controls the land, who finances growth and how many publicly traded builders remain.
The next chapter of U.S. homebuilding consolidation may have less to do with mortgage rates, near-term sales volumes, or even the availability of acquisition targets than with a fundamental, high-level shift in who wants to own American housing businesses, how long they plan to hold them, and what they expect their capital to accomplish.
Global strategic investors, including Japanese corporations and Berkshire Hathaway, have been investing billions in U.S. residential real estate even as domestic builders contend with affordability constraints, slower absorption and margin pressure.
Meanwhile, institutional capital is moving deeper into residential land financing and build-to-rent development, reshaping the economics of how homes are produced and who assumes the risks along the way.
The forces connect. Together, they point toward a housing industry in which operating scale, access to patient capital and the agility to deploy capital across multiple residential business models increasingly determine competitive advantage.
That was the central signal from a capital markets and M&A discussion at the recent Zelman Housing Summit, moderated by Tony McGill, senior managing director and head of investment banking, and Haitham Said, managing director.
The discussion raised a key question for homebuilding executives: Will there be fewer publicly traded homebuilders by the end of 2027, and will some of today’s strongest privately held operators become part of much larger, globally financed enterprises?
The money is moving, even when housing demand isn’t
McGill’s opening presentation established a striking divergence between capital markets activity and housing’s operating environment.
Through August 2026, the dollar value of U.S. housing-related M&A transactions had increased 56% from the comparable 2025 period, according to Bloomberg data presented by Zelman. Across industries, M&A dollar volume increased 76%.
At the same time, investment-grade debt issuance in the housing sector fell 71% year over year. The industry attracted acquisition capital, while companies remained reluctant to issue new debt amid elevated borrowing costs.
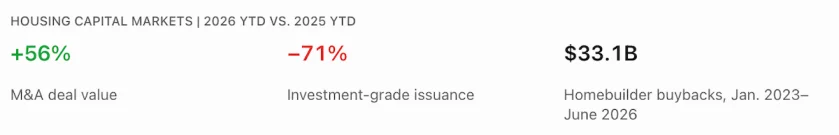
The contrast extends to share repurchases. Publicly traded homebuilders repurchased $33.1 billion of their own stock from January 2023 through June 2026, using cash generation and balance-sheet resources to reduce outstanding equity rather than pursuing external growth exclusively.
That presents a revealing capital-allocation choice. A builder can return capital to shareholders, acquire competitors, invest in land, or deploy the same resources through structures that support a larger production platform.
For globally financed strategic buyers, the calculation can look different. An acquisition made during a weak operating cycle can secure market position, talent, land access, and operating infrastructure, whose value may not become fully apparent for years.
McGill characterized the major transactions as reflecting confidence in housing’s longer-term prospects, rather than its immediate performance.
Patient capital is replacing shorter-term capital
One of the discussion’s most important distinctions concerned the buyer’s investment horizon.
Warren Krug, Executive VP and chief investment officer of Brookfield Residential, described the ownership transition underway:
“I think what you’re seeing in some of the larger transactions this year is that you’re replacing some of the more transient private equity-type capital, which is coming out of private markets, with buyers like Berkshire and some Japanese groups who are longer dated.”
The implication is that buyers investing over a five- or 10-year operating horizon can justify a transaction differently than investors seeking a relatively near-term exit.
Daiwa House’s expansion through Stanley Martin Homes demonstrates the operating logic. Eric Marks, Stanley Martin’s M&A team leader, described a business targeting 10,000 closings in 2027, with three recent acquisitions expected to contribute approximately $1 billion in revenue.
The Holiday Builders acquisition expanded Stanley Martin’s Florida footprint from two divisions to eight. The transaction’s stream of future earnings met one objective, and, equally important, the new combination with Holiday Builders adds an established, locally competent operating network in a market where large independent acquisition candidates have become increasingly scarce.
As Marks notes, an acquiror’s strategic objectives can sometimes influence valuation.
For owners evaluating a sale, the wake-up call is to recognize that a buyer seeking immediate geographic scale may value an enterprise differently than one primarily underwriting a current earnings multiple.
It also places a premium on integration. Marks indicated that Stanley Martin and Japan-based parent company Daiwa House expect to temporarily slow its single-family acquisition pace while absorbing its recent purchases. Even patient capital cannot eliminate the operational demands of integrating businesses.
Land banking becomes a growth business of its own
The same capital-efficiency imperative is transforming residential land development.
Steve Benson, founder and CEO of Essential Housing, described land banking as financing land as it moves through development toward finished, buildable lots. Instead of tying up its own capital throughout that process, a builder can use a land bank to fund acquisition and improvements, then purchase finished lots on an agreed schedule.
Benson estimated that his firm’s land banking arrangements typically cost builders about 200 to 250 basis points above their blended cost of debt and equity capital, typically translating to a slightly lesser impact to gross margin, depending on project economics.
The trade-off centers on capital productivity.
In Benson’s illustration, the capital required to develop 150 homes independently could support about 450 homes through land banking. The builder might earn a 23% gross margin rather than 25%, but generate substantially more total gross profit across the expanded production base.
That outcome depends on identifying sufficient profitable projects, maintaining absorption and managing lot-purchase obligations. Land banking expands capacity; it does not create demand or eliminate development risk.
Benson also disclosed that Essential Housing had originated more than $22 billion in land-bank investments over five years and was raising additional capital to support approximately $10 billion in future investments.
Brookfield has pursued a complementary strategy, acquiring land-development capabilities and investing in operators before buying their businesses outright. Its Newland and Kolter transactions illustrate how land expertise, local relationships and development pipelines can themselves become acquisition targets.
The emerging distinction is that institutional capital is no longer merely financing builders’ land positions; it is ramping up its strategic and operational engagement on a grand scale. Increasingly, it is financing, owning, and consolidating the infrastructure through which builders secure their future supply.
Build-to-rent enters its next institutional phase
Build-to-rent offers another illustration of capital reshaping housing production.
Scott Eisen, executive vice president and chief investment officer of Invitation Homes, explained that the company’s acquisition of ResiBuilt reflected a strategic decision to move beyond purchasing finished homes from builders.
The acquisition brought land sourcing, construction management and development expertise inside an established rental ownership and operating platform.
Invitation Homes can now control more of the production process, develop homes for its own portfolio and potentially serve institutional joint-venture partners.
The broader BTR sector faces a different challenge. After significant private equity investment during its early expansion, new capital allocations slowed as rental supply increased and regulatory uncertainty surrounding institutional single-family ownership intensified.
Eisen suggested that greater clarity around the distinction between newly constructed rental homes and acquisitions of existing homes could help reactivate sidelined capital. The timing and extent of that recovery remain uncertain.
For production builders, the opportunity extends beyond selling completed communities to rental investors. BTR may increasingly involve development partnerships, dedicated construction platforms and longer-term relationships with institutional owners.
Will there be fewer public homebuilders in 2027?
McGill posed that question directly to the panel, and the discussion suggested that the answer could be yes.
The logic extends beyond conventional consolidation. Publicly traded builders with limited scale, relatively high corporate overhead, or insufficient geographic concentration may find that their businesses hold greater strategic value within larger organizations than as standalone public enterprises.
Long-duration capital creates additional potential buyers, while weak operating conditions can make valuations more attractive.
Still, consolidation will not proceed uniformly. Some acquirers must digest recent transactions, and the advantages of scale depend on disciplined integration, purchasing leverage, and local execution.
The more meaningful development may be a gradual redistribution of control across the housing production ecosystem. Global strategic investors are acquiring operating platforms. Institutional land capital is financing the next generation of communities. Rental owners are integrating development and construction capabilities. Meanwhile, public builders are deciding whether their capital creates more value through acquisitions, organic expansion or share repurchases.
For homebuilding leaders, the strategic question is no longer simply whether to buy, sell or remain independent. It is now about whether their businesses have the market position, operating capabilities, capital relationships and organizational capacity to compete as the industry’s ownership structure changes.
The next phase of consolidation may be less about the number of companies building homes than about who controls the capital, land and operating systems that make homebuilding possible.